A project can look profitable until the bills that keep your business running start showing up. Rent, software subscriptions, manager time, insurance, equipment, and office support may not appear on a customer invoice, but they are real costs of delivering the work. When you allocate overhead to projects, you get a more honest view of what each job contributes to your business.
That does not mean every expense needs a complicated formula. The goal is a method your team can understand, repeat, and review without spending more time on calculations than on serving customers.
Why project overhead changes your decisions
Direct costs are usually easy to see. Labor logged to a job, materials purchased for a client, subcontractor invoices, and shipping costs belong directly to a project. Overhead is different. These are shared operating costs that support more than one project or the company as a whole.
If you only compare project revenue with direct costs, you may overstate margins. A $20,000 project with $11,000 in direct labor and materials appears to generate $9,000. But if the project used a meaningful share of your project manager's time, software licenses, warehouse space, or administrative support, its actual contribution is lower.
This visibility matters when you set prices, decide which customers to pursue, evaluate project managers, and plan hiring. It also helps identify jobs that look busy but do not produce enough return after shared costs. For a growing business, that is often the difference between more revenue and healthier cash flow.
Start by separating direct costs from overhead
Before assigning anything, make sure your expense records are organized consistently. A cost should be direct when you can reasonably trace it to one project without extra assumptions. For example, job-specific lumber, a freelancer hired for one website build, or mileage for a customer visit can be posted directly to that project.
Overhead includes expenses that support several projects, such as accounting software, general office rent, business insurance, supervisors who oversee multiple jobs, internet service, and depreciation on shared equipment. Some costs sit in the middle. A project manager who works 80 percent of the month on one implementation and 20 percent on general planning may have part of their cost assigned directly and part treated as overhead.
The key is consistency. Do not label an expense direct on one job and overhead on another just because a project needs a better margin. Write down your rule, apply it across comparable projects, and revisit it when the way you work changes.
Build useful overhead cost pools
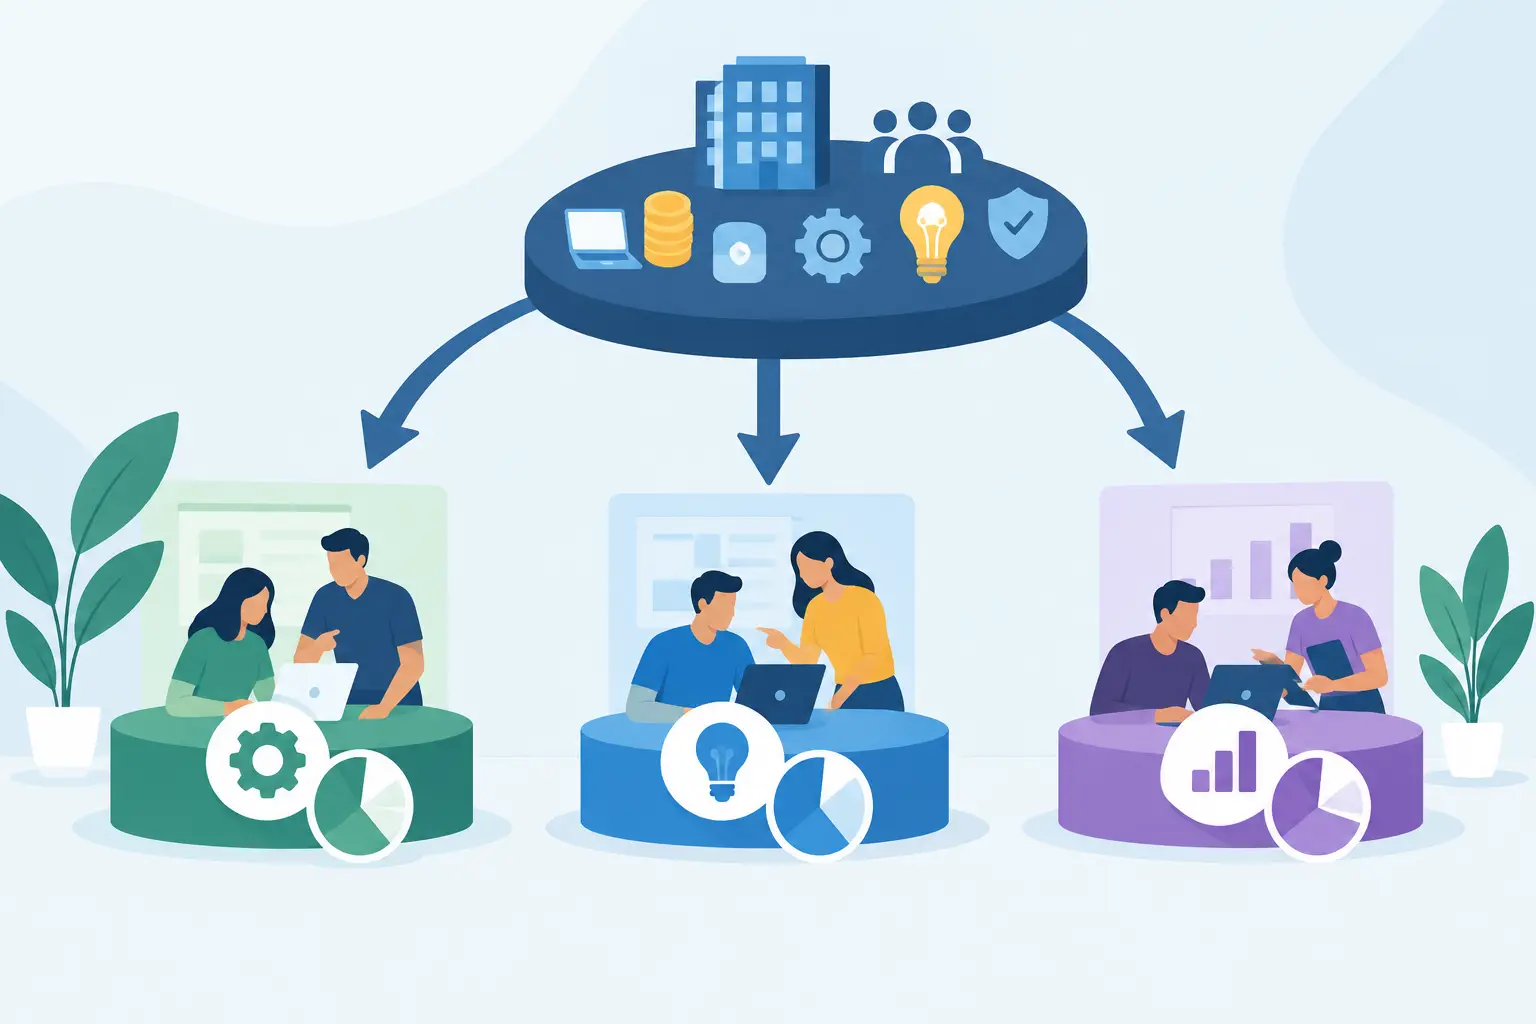
Putting all overhead into one large bucket is simple, but it can distort project results. A consulting engagement may use little warehouse capacity, while a product installation may use a great deal. Grouping similar shared expenses into cost pools gives you better information without forcing you into enterprise-level accounting.
A practical business might create separate pools for administrative support, facilities and equipment, technology, and project supervision. Administrative support can include bookkeeping, reception, and general management. Facilities and equipment may include rent, utilities, maintenance, and equipment depreciation. Technology can include shared software and communications tools. Project supervision can include team leads who coordinate several active jobs.
You do not need every expense in a separate pool. Start with the categories that are large enough to influence pricing or that vary significantly from project to project. A small monthly subscription that every employee uses may be fine in a general overhead pool. A costly specialized machine probably deserves its own treatment.
How to allocate overhead to projects using the right driver
An allocation driver is the activity used to share a cost pool among projects. The best driver has a clear relationship with the expense. It does not need to be perfect. It needs to be reasonable, practical to track, and stable enough to use from month to month.
Common drivers include:
- Direct labor hours for supervision, payroll support, and labor-intensive operations
- Direct labor cost when projects use similar employee roles but pay rates differ
- Machine hours for equipment maintenance, shop utilities, or equipment depreciation
- Material or inventory value for storage, purchasing, and handling costs
- Revenue when projects use shared resources in broadly similar ways and detailed tracking is not practical
For example, assume your company has $12,000 in monthly project-support overhead. Your team logged 600 direct labor hours across all projects. The overhead rate is $20 per direct labor hour. A project that used 75 labor hours receives $1,500 of allocated overhead.
The calculation is straightforward: total cost pool divided by total driver activity equals the overhead rate. Multiply that rate by the activity used by each project. If a project had $8,000 in revenue and $5,000 in direct costs, the additional $1,500 in overhead shows that its project profit is $1,500, not $3,000.
Revenue can be a useful driver for very small businesses that do not yet track hours or equipment use. However, it may mislead you if a high-revenue project requires little internal effort or a lower-revenue project consumes a large amount of labor. When possible, choose a driver connected to how the cost is created.
Use rates that match your operating rhythm
You can calculate allocation rates monthly, quarterly, or annually. Monthly rates keep results current when payroll, rent, staffing, or workload changes frequently. Annual rates are easier to budget and can reduce swings caused by a slow week or a single large invoice.
Many businesses use a planned rate during the year. They estimate annual overhead and expected activity, then apply a consistent rate to projects as work is completed. At month-end or quarter-end, they compare planned overhead with actual results and adjust if needed.
This approach is especially helpful for pricing. If you wait until a project ends to discover that shared costs were higher than expected, you cannot change the original quote. A working overhead rate lets you include a realistic share of operating costs before you send the proposal.
There is a trade-off. A highly detailed model can be more precise, but only if your data is accurate and your staff follows the process. For many small and medium-sized businesses, two to four cost pools and a few reliable drivers provide better decisions than a complicated model no one maintains.
Keep the process connected to daily records
Overhead allocation depends on clean source data. Employees need a simple way to record time by project. Materials, inventory movements, vendor bills, and reimbursements should be coded to the correct project whenever they are direct costs. Shared bills should be recorded in the appropriate overhead category rather than left as uncategorized expenses.
A cloud accounting system can make this routine easier by keeping project income, direct costs, expenses, invoices, and supporting documents in one place. In MyCloudBook, teams can track project earnings alongside income and expense activity, giving managers a clearer starting point for reviewing margins and shared costs.
Set a regular review point, such as the end of each month. Check whether total recorded overhead looks complete, whether activity totals are realistic, and whether any project has an unusual result. A project with a negative margin is not always a mistake. It may have required extra rework, customer support, or management attention. The allocation helps you ask the right questions.
Avoid the mistakes that make margins unreliable
The most common mistake is allocating only a few easy costs and ignoring the rest. Excluding payroll taxes, shared software, owner or manager time, insurance, and equipment costs can make every project look stronger than it is.
Another problem is using one driver for everything. Direct labor hours may work well for supervision but poorly for warehouse costs driven by inventory volume. You do not need a separate formula for every expense, but large cost categories should reflect the resources projects actually consume.
Also avoid treating allocation results as a final verdict on a customer or employee. Some strategic projects have lower margins for valid reasons. A first project with a new customer may require extra setup. A job can create a portfolio asset, support a long-term account, or help keep a specialized team productive. Use the numbers to guide decisions, then apply business judgment.
Finally, do not let overhead allocations replace cash flow tracking. A profitable project can still create a cash strain if you purchase materials early and collect payment late. Review invoice status, payment timing, and upcoming bills alongside project profitability.
Make better pricing decisions before work begins
Once you know your typical overhead rate, add it to estimates before approving a job. Start with direct labor, materials, subcontractors, and other project-specific costs. Apply the appropriate overhead based on expected hours, machine time, material handling, or the driver you use. Then add the profit margin your business needs.
This gives your sales and project teams a common baseline. They can still make a deliberate exception for a key customer or competitive bid, but the exception is visible. Instead of accidentally underpricing work, you can decide knowingly whether a lower margin makes sense.
A fair allocation method will not make every project perfectly predictable. It will give you a dependable view of the work your business is truly doing and the costs required to support it. Start with a method your team can maintain, review it regularly, and let clearer project margins lead your next pricing conversation.